
AMRO warns external shocks and construction slump threaten Cambodia’s growth path
AMRO warns external shocks and construction slump threaten Cambodia’s growth path
With the regional financial system growing more interconnected, the assessment highlights three policy imperatives for Cambodia: shore up the property and banking sectors, strengthen financial resilience buffers and develop deeper capital markets.
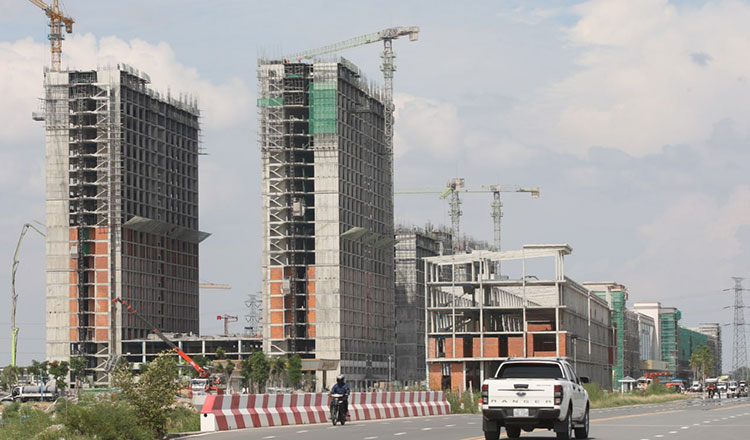
The ASEAN+3 Macroeconomic Research Office (AMRO) has identified three financial stability concerns for Cambodia, linking real estate weakness to banking risks, global financial cycles to external shocks, and uneven capital-market development to deeper regional integration.
The assessment was made in the ASEAN+3 Financial Stability Report (AFSR) 2026, released Monday, which examined the region’s financial resilience amid heightened global uncertainty and changing financial linkages.
The report’s first chapter, “Navigating Spillovers from Global Shocks – Why Fundamentals Matter,” identified Cambodia among frontier economies facing elevated banking-sector vulnerabilities, with prolonged weakness in the real estate sector weakening asset quality and increasing non-performing loans (NPLs).
“Although these vulnerabilities are largely domestic, they could amplify the transmission of future external shocks if global financial conditions tighten,” the AFSR 2026 said.
AMRO placed Cambodia alongside Laos and Vietnam among economies where financial stability risks remain uneven. The Kingdom is also identified as more vulnerable to US dollar volatility because of property-sector, debt or external financing constraints.
By contrast, economies with deeper domestic investor bases, ample foreign exchange reserves, credible policy frameworks and well-developed local-currency bond markets are better positioned to absorb periods of heightened US dollar volatility, the report added.
Cambodia was also included in the report’s regional comparisons of total and Tier-1 capital adequacy ratios, based on data from the second quarter of 2025, and NPL ratios, based on data from the third quarter last year.
The banking-sector vulnerabilities identified in the first chapter form part of a wider regional financial environment in which external conditions can affect economies through capital flows, exchange rates and financing costs.
This was examined in the second chapter, ‘Riding the Same Wave? Financial Cycle Synchronization and Spillovers in ASEAN+3’. The chapter assesses how closely ASEAN+3 economies move with the global financial cycle and how global financial conditions are transmitted through external liabilities and financial markets.
It found that regional financial conditions have become less synchronised with the global financial cycle outside periods of major stress, although global factors remain particularly influential during heightened stress episodes.
Cambodia was also included in the report’s external-liabilities analysis alongside China, Hong Kong, Japan, South Korea, Indonesia, Malaysia, the Philippines, Singapore and Thailand.
The Kingdom is grouped with Indonesia, Malaysia, the Philippines and Thailand under ‘ASEAN ex-SG’ in the analysis of external-liability composition.
The analysis pointed to a rising share of direct investment in the group’s external liabilities. AMRO noted that direct investment is generally less market-sensitive than portfolio investment, which can help moderate exposure to global financial-cycle movements.
Cambodia also appears in the report’s regional assessments of foreign exchange reserve adequacy, capital adequacy, NPL ratios, liquidity coverage ratios and fiscal space.
While the second chapter examined how financial conditions and shocks are transmitted across economies, the third looks at how deeper financial markets and greater regional integration could strengthen resilience.
The third chapter, ‘Advancing ASEAN+3 Financial Market Integration – The Role of Digital Financial Platforms’, examined the region’s relatively limited financial integration compared with its deep trade and investment linkages.
The report found that development of bond and equity markets remains uneven. The Plus-3 economies of China, Japan and South Korea lead local-currency bond-market development, while the BCLMV economies of Brunei, Cambodia, Laos, Myanmar and Vietnam lag behind.
Equity-market development is also concentrated in a small number of large markets, with much of ASEAN still having substantial room to deepen its equity markets, AMRO said. The report examined digital financial platforms as a way to improve cross-border connectivity, settlement efficiency and investor access.
However, the regional body cautioned that technology alone cannot overcome legal, regulatory and institutional barriers, meaning digital platforms should complement broader efforts to deepen regional capital markets and strengthen financial infrastructure.
Taken together, the three chapters pointed to interconnected financial stability challenges, from domestic banking vulnerabilities and exposure to global financial conditions to uneven capital-market development.
For Cambodia, the report’s assessment highlights the importance of addressing vulnerabilities in the property and banking sectors while strengthening financial buffers and developing deeper capital markets as the regional financial system becomes increasingly interconnected.
The AFSR 2026 is based on information generally available through August 27, although the reporting period varies across individual indicators.
- 07:51 08/10/2026