
New liquidity rules offer lending headroom but funding pressures persist
New liquidity rules offer lending headroom but funding pressures persist
Circular 50/2026/TT-NHNN raises the maximum loan-to-deposit ratio (LDR) to 95 per cent from currently 85 per cent while introducing a phased transition towards Basel III liquidity standards.
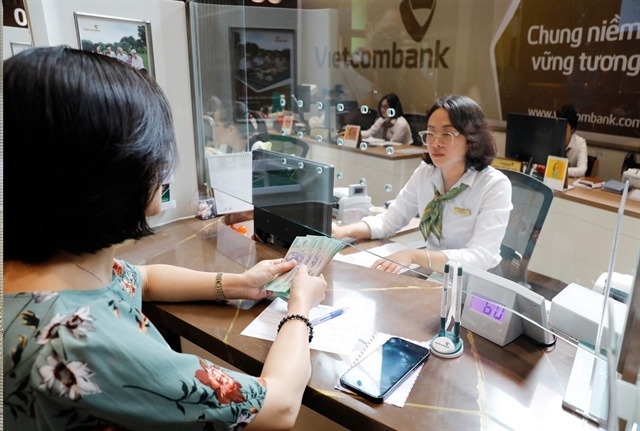
Transactions at the head office of Vietcombank in Hà Nội. The maximum loan-to-deposit ratio (LDR) will be raised to 95 per cent from currently 85 per cent with an aim to help banks manage liquidity more effectively. — VNA/VNS Photo Trần Việt |
New banking regulations will give lenders greater flexibility to expand credit and could ease competition for deposits, but analysts say the changes will not resolve the underlying funding pressures created by lending growth outpacing deposit mobilisation.
Circular 50/2026/TT-NHNN, issued by the State Bank of Vietnam on September 30 and scheduled to take effect on December 1, raises the maximum loan-to-deposit ratio (LDR) to 95 per cent from currently 85 per cent while introducing a phased transition towards Basel III liquidity standards, including the liquidity coverage ratio (LCR) and the net stable funding ratio (NSFR).
The changes come as credit growth accelerates and banks face increasing pressure to secure stable, longer-term funding. Outstanding credit reached about VNĐ20.6 quadrillion (US$782 billion) as of September 28, up 13.2 per cent from the end of 2025.
“The new framework will help banks manage liquidity more effectively, thereby avoiding a widespread race to mobilise funds,” said Quản Trọng Thành, head of research at Maybank Investment Bank Securities Vietnam.
Conditional relief
Under Circular 50, lenders can continue operating under the existing framework, with an 85 per cent LDR ceiling, during the transition period. The new framework is scheduled to become mandatory from October 2028 although eligible banks may adopt the revised requirements earlier.
The regulation also introduces two Basel III measures. The LCR assesses a bank’s ability to withstand short-term liquidity stress by holding sufficient high-quality liquid assets, while the NSFR measures whether its funding profile is sufficiently stable relative to its assets and off-balance-sheet exposures.
The minimum LCR will begin at 50 per cent in October 2028 and rise by 10 percentage points annually to reach 100 per cent in October 2033. The NSFR will start at 90 per cent, increase to 95 per cent in 2029 and reach 100 per cent in 2030.
Banks that meet the full 100 per cent requirements for both ratios will no longer be subject to the LDR ceiling under the new framework.
The impact is not uniform.
Capital strength, funding structures and the ability to comply with the new liquidity requirements will determine which banks are best positioned to take advantage.
ACB Securities said banks with substantial eligible capital and foreign funding could gain additional lending capacity, while lenders with large amounts of assets excluded from the revised LDR calculation or heavy reliance on short-term funding could face tighter constraints.
Maybank Investment Bank Securities cited Techcombank, HDBank, VPBank, ACB and MSB among banks that could be better placed to adapt because of their progress in risk management and international funding relationships.
SSI Research identified Techcombank, MB, VPBank, Vietcombank, BIDV and MSB among the lenders that could benefit from the expanded lending headroom.
Raising the LDR ceiling to 95 per cent provides short-term relief for banks and encourages improvements in liquidity management but does not automatically mean lenders have more cash available to disburse, the company said.
If credit continues to grow faster than deposits, banks will still need to mobilise additional funds through deposit-taking, foreign borrowing or bond issuance. Their ability to turn regulatory headroom into actual lending will also depend on borrower demand, credit quality and the credit-growth limits.
Deeper capital market needed
Transactions at the head office of Vietcombank in Hà Nội. The maximum loan-to-deposit ratio (LDR) will be raised to 95 per cent from currently 85 per cent with an aim to help banks manage liquidity more effectively. — VNA/VNS Photo Trần Việt |
Analysts say the longer-term solution to Việt Nam’s banking sector funding pressures lies in developing alternative sources of capital to reduce the economy’s reliance on commercial banks.
Data cited by securities analysts show that the average LDR among 27 listed banks rose by 118 basis points in the second quarter of 2026 from the previous quarter and by 255 basis points from the end of 2025.
The increase highlights growing pressure on lenders to balance credit expansion with available funding, even as many banks remained below the previous regulatory ceiling under the applicable calculation method.
Trần Bá Duy, investment advisory director at VPS Securities, said Circular 50 would support longer-term liquidity management but would not resolve the underlying mismatch between short-term funding and longer-term lending.
Developing the capital market more effectively had become critical, Duy said, adding that solutions are needed to channel household savings into appropriate sources of long-term funding, including bond markets, pension funds and insurance funds.
However, developing these channels would require a broader investor base, stronger market confidence and greater financial literacy would be essential to building a balanced and sustainable capital market, he said.
Circular 50 is expected to have positive impacts on the banking system over the medium to long term, although its near-term impact is expected to be limited and uneven, according to Virtus Prosperity.
The broader challenge remains whether Việt Nam can develop alternative sources of long-term capital quickly enough to reduce the burden on commercial banks. Without that structural shift, the new liquidity rules may improve regulatory flexibility without fully resolving the funding pressures underlying the system.
Thành said sustainable financing for the economy would depend on expanding funding sources, attracting foreign direct investment (FDI), mobilising international capital and unlocking underutilised funding pools.
Improving Việt Nam’s sovereign credit rating would also help the Government, banks and businesses access international capital at lower costs, Thành said.
- 08:24 12/10/2026