
AI to transform the future of finance
AI to transform the future of finance
Financial heads around the world must contend with the AI era. Mohammad Mudasser, partner of Deals Transformation at PwC Vietnam, looks at how it could help shape tomorrow’s business decisions.
For years, finance leaders have been asked to produce faster, more reliable information while maintaining control, accountability and confidence in the numbers. In most boardrooms, finance is still expected to explain yesterday's performance.
By the time monthly reports are finalised, the underlying business may already have changed. Customer demand may have shifted, inventory may be building in the wrong locations, and cash collections may no longer reflect assumptions made only weeks earlier.
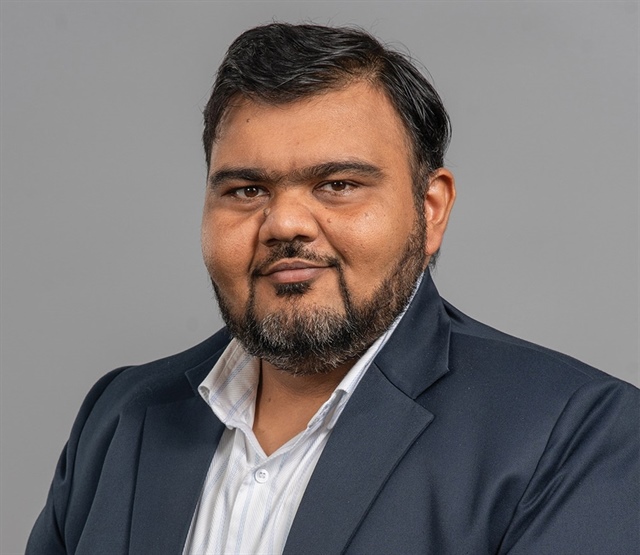
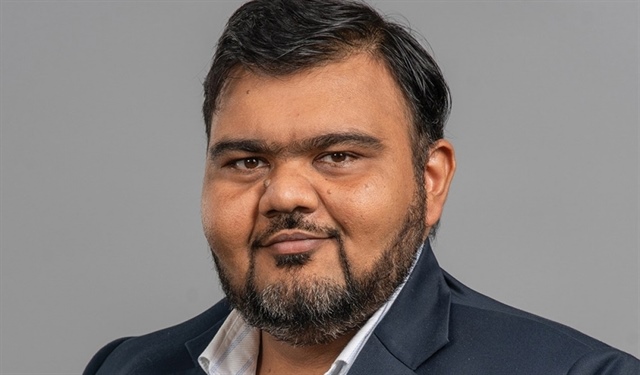
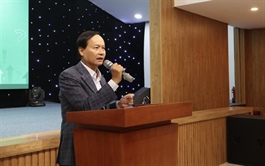
Mohammad Mudasser, partner of Deals Transformation at PwC Vietnam |
The question confronting CFOs is whether AI can help finance identify those changes while there is still time to act. More fundamentally, can it help finance move beyond reporting performance to shaping business decisions?
For CFOs, that value will not be measured by the number of tools introduced or processes automated, but by whether AI helps finance identify emerging issues, test scenarios and bring financial and operational information together in time for management to act.
Early investment in AI for finance has focused largely on productivity: automating reports, extracting information, accelerating reconciliations, and reducing repetitive work. These improvements remain valuable, particularly where finance teams spend more time preparing information than interpreting it. But they represent only part of the opportunity.
In our experience, the constraint is rarely the absence of technology. More often, finance, sales and operations are working from different assumptions. A forecasting model may assume inventory is available for sale, while commercial teams know certain stock has already been committed. Credit exposure may appear manageable in finance reports while sales teams are negotiating payment extensions. Introducing AI into that environment can accelerate analysis, but it can also accelerate disagreement.
One misconception is that AI changes finance because it produces better answers. In reality, it changes finance because it changes when questions can be asked. Instead of waiting until month-end to identify a problem, management may be alerted while corrective action is still possible. The challenge then becomes organisational rather than technical: who owns the decision and what happens next?
AI-enabled finance function
An AI-enabled finance function should be judged not by the number of tools it has purchased, but by whether it gives decision-makers better information when it matters. In practice, AI could alert treasury to collection risks, help the financial planning and analysis team test changing assumptions or direct controllers towards unusual transactions.
Treasury and working capital are practical starting points because the outcomes are concrete and measurable. By combining payment behaviour, sales and purchasing data, inventory movements and operational assumptions, AI can flag cash receipts at risk, excess inventory absorbing capital or forecasts that no longer reflect current evidence.
For example, a deteriorating collection pattern from a key distributor might not justify immediate intervention. However, if the same signal appears alongside slowing sales and rising inventory in a specific region, management's response may be very different. Finance increasingly becomes responsible for connecting these signals rather than reporting them separately.
During one retail transformation, the objective was not to build a more sophisticated forecast. The challenge was that inventory, sales and receivable information existed across multiple channels and was interpreted differently by different business functions. The lesson was simple: before improving the forecast, management first had to agree on what the business was actually measuring.
Yet the output is only as dependable as the process behind it. Reliable data, visible assumptions and human judgement remain essential; finance leaders must still challenge recommendations, consider the business context and retain accountability for the final decision.
PwC’s collaboration with OpenAI to develop AI-enabled workflows across planning, forecasting, treasury, procurement, tax and reporting illustrates this direction of travel. The intention is to embed AI within finance processes rather than add it as a separate layer.
Across many Vietnamese organisations, transformation ambitions extend beyond finance. Businesses are trying to connect commercial operations, customer channels, supply chains and finance onto a common platform. Yet the technology challenge is often secondary to a business challenge: different functions have developed their own definitions, reports and ways of making decisions over many years.
This is particularly common in fast-growing organisations that have expanded across multiple channels, locations or business units faster than their underlying operating model has evolved.
We have seen this in projects involving retail and distribution businesses where management sought a real-time view of inventory, pricing and customer activity. The harder discussion was often not how to build the dashboard, but which numbers should be trusted and who should own the resulting decision. AI will not eliminate those debates. It may simply reveal them earlier.
In one retail and distribution transformation, management's ambition extended beyond reporting and into a digitally integrated operating model capable of linking customer interactions, inventory movements, pricing decisions and finance information. The critical lesson was that technology created value only after ownership, definitions and decision rights had been clarified across functions.
Risks and priorities for CFOs
The more immediate risk for many organisations may not be moving too slowly on AI. It may be introducing AI into processes that already suffer from unclear ownership and inconsistent data. Doing so can create the appearance of confidence without improving the quality of the underlying decision. Before asking whether a model is intelligent, leaders should ask whether the underlying process is sufficiently trusted to support a business decision.
For Vietnamese CFOs, moving finance from reporting the past to shaping what the business does next requires action in four areas: decisions, foundations, people, and value.
First is to focus AI investment on a clearly defined business decision where better information could improve a financial outcome. Potential starting points include cash forecasting, overdue receivables, inventory exposure, scenario planning and capital allocation. Define the decision, the current problem and the accountable executive before selecting the technology.
Second is to establish the process and data foundations required to support the selected decision. AI will not resolve unclear ownership, inconsistent definitions or disconnected workflows. Finance and the business must agree on the source of truth, process and control points, while ensuring that the minimum data required for a pilot is reliable and clearly owned.
Third is to define how people will use, challenge and remain accountable for outputs. Each use case should specify who reviews and may override a recommendation, what evidence is required and how the decision is recorded. Employees should help shape the design because they understand exceptions that may not appear in system data. Leaders should also be clear about whether the objective is to remove repetitive work, strengthen control, increase decision capacity or reduce cost.
And finally, it is necessary to measure value through a business outcome linked to the decision. Senior management teams rarely celebrate a model because it is technically accurate. They value it because a better decision was made faster, with greater confidence and fewer surprises. For that reason, CFOs should measure AI against business outcomes rather than system activity.
Over the past decade, finance has become faster, more automated and more data-rich. The next challenge is different. It is helping organisations make better decisions under increasing uncertainty. AI will contribute to that shift, but technology alone will not determine who succeeds.
The organisations that succeed will be those that combine trusted data, accountability and sound judgement. Their advantage will not lie in the sophistication of AI models, but in ability to recognise change earlier, allocate capital more effectively and make decisions with greater confidence when market conditions shift.
- 09:04 19/10/2026