
Vietnam’s bank stocks enter a new phase of selective gains
Vietnam’s bank stocks enter a new phase of selective gains
Bank stocks are attracting renewed interest as market upgrades draw foreign capital, but gains will be selective. Ngo The Hien, deputy director of the Analysis Centre at Saigon-Hanoi Securities, told VIR’s Nhue Man that growth quality, profitability, and management will increasingly drive valuations.
After the recent divergence, how do you assess the current valuation levels of bank stocks? For those already trading at high valuations, what conditions would be needed for further gains?
|
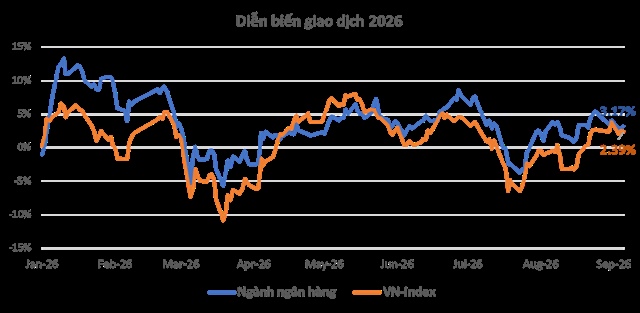
According to our data, the banking sector’s stock price performance since the beginning of the year has broadly tracked the overall market. As of September 9, bank stocks had gained 3.17 per cent, compared with a 2.39 per cent increase in the VN-Index.
Based on the financial statements released for the first six months of the year, total net profit after tax at 27 listed banks increased 19.6 per cent on-year. We forecast that the banking sector’s aggregate profit could grow by 16–18 per cent for the full year, below the 19.5 per cent growth recorded in 2025.
Looking at the sector’s price performance, I believe the market is taking a relatively cautious view of bank stocks. The sector’s current price-to-book ratio stands at 1.42x, compared with a 10-year average of 1.7x. In 2025, the sector-wide index gained 29.8 per cent.
This is partly because market liquidity is no longer as abundant as it was last year. Investors are also concerned that the banking sector is facing a less favourable business environment.
At the individual stock level, price divergence has been quite pronounced, with only nine of the 27 stocks outperforming the VN-Index. Stock prices, in banking and across the market, can rise over a given period for various reasons. Beyond sector-wide expectations, individual corporate catalysts can include capital increases, merger and acquisition expectations, or exceptional earnings growth.
However, over the longer term, a company’s business growth prospects will remain the primary factor supporting its share price.
Source: Saigon-Hanoi Securities |
What will be the main drivers of bank profit growth through the end of the year? Where is there still room for positive surprises?
This year, the State Bank of Vietnam (SBV) has adopted a cautious approach to credit management, targeting credit growth of 15 per cent, below the 19 per cent recorded in 2025.
As of July 31, total system credit stood at approximately $812 billion, up 8.98 per cent from the end of 2025, leaving room for further growth in the remaining months of the year.
Since the end of Q2, monetary policy has gradually shifted towards targeted support as exchange-rate and energy-price pressures have eased. Measures including the special mechanism excluding outstanding loans to 18 key projects from banks’ credit growth limits; Circular No.25/2026, raising the cap on the use of short-term funds for medium- and long-term lending from 30 to 40 per cent; and Decision No.1743/QD-NHNN, which allows banks to count 50 per cent of the State Treasury’s term deposits towards total deposits when calculating the loan-to-deposit ratio, together with a range of other technical measures, have helped improve system liquidity.
In addition, stronger fiscal policy support in the final months of the year, with more than $21.8 billion in public investment funds still awaiting disbursement, will support credit growth across the banking sector in the period ahead.
With credit growing rapidly, what risks does this pose to bank profits? Which indicators should investors monitor to identify emerging asset-quality pressures?
Alongside balance-sheet expansion, credit quality is another area investors need to watch closely.
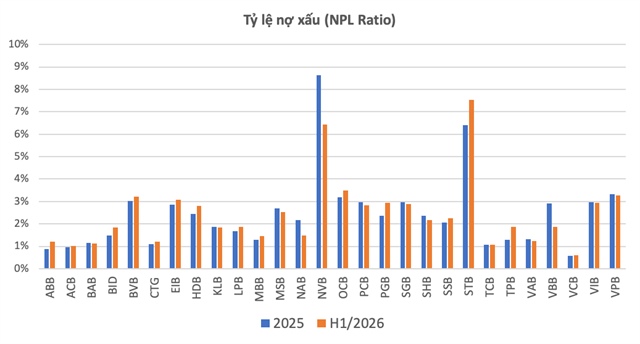
Among 28 listed banks, total outstanding balances in non-performing loan groups 3-5 had increased 17.5 per cent by the end of Q2 from the end of 2025, while group 2 loans had risen 28.97 per cent.
The rise in bad debt has forced banks to increase provisioning, with total credit-loss provisions in the first six months of the year up 20 per cent from the same period in 2025.
In addition, to maintain operating efficiency amid rising deposit rates and strong pressure from the SBV to comply with efforts to lower lending rates, banks will need to restructure loan maturities, diversify revenue streams, increase the use of digital transformation and AI to optimise costs, and strengthen their capital base through funding from the stock market, offshore borrowing and other channels.
Source: Saigon-Hanoi Securities |
How will FTSE-related capital flows affect bank stocks? What will determine whether active foreign capital continues to stay in the market?
According to FTSE Russell, 27 stocks, including eight bank stocks, are expected to be included in the FTSE Global Equity Index Series, effective September 21.
With Vietnam’s weighting expected to rise to around 0.49–0.5 per cent from 0.34–0.35 per cent at the March 2026 review, passive capital inflows from index-tracking funds are forecast to reach $2–2.5 billion after all four phases are completed by September 2027. The eight bank stocks are expected to account for around 58 per cent of the inflows, although the allocation will vary by stock.
However, with the first phase accounting for only 10 per cent of the total allocation, I do not expect a significant impact on stock prices at this stage.
In the longer term, market upgrading should be viewed as a starting point for the broader market and individual companies to move towards higher standards. Beyond passive funds, the ability to retain active foreign capital will continue to depend on the investment environment, macroeconomic and corporate prospects, and progress in implementing reforms and upgrading the capital market in line with the broader development strategy.
If Vietnam can build a capital market with a diverse range of products, greater depth, integrated and seamless infrastructure, transparency, strong investor protection mechanisms, and timely detection and enforcement of violations, the country will retain existing foreign capital while attracting additional inflows from overseas.
Over the next 6–12 months, what will differentiate banks?
The outlook for the next 6–12 months can be summed up in three keywords: growth, divergence and caution.
Growth will remain the dominant trend, driven by strong credit demand, particularly for infrastructure development projects. Divergence will become more pronounced among banks based on management capabilities, asset quality and funding costs. Meanwhile, caution will stem from the need to balance the objective of supporting economic growth with maintaining liquidity, controlling risks and preserving financial stability.
This will be a period in which management effectiveness, rather than growth alone, determines each bank’s position in the new cycle.
Against this backdrop, banks with strong capital buffers, solid funding bases, sound credit and cost management capabilities, and structural advantages in fee income will have greater opportunities to grow faster than the sector as a whole.
- 14:00 14/09/2026