
Fintech growth puts financial stability and resilience in focus
Fintech growth puts financial stability and resilience in focus
Rapid advances in fintech and AI are creating opportunities to improve efficiency and expand financial inclusion, but also intensifying the need for stronger risk management and operational resilience across the financial system.
As digital technologies become increasingly embedded in financial services, they are reshaping not only how products are delivered but also the business models, operational structures, and risk management practices of financial institutions. However, greater reliance on digital platforms, data, and interconnected technology systems also creates new vulnerabilities. A technical disruption at one institution can quickly develop into a broader operational or reputational problem, potentially undermining market confidence and financial stability.
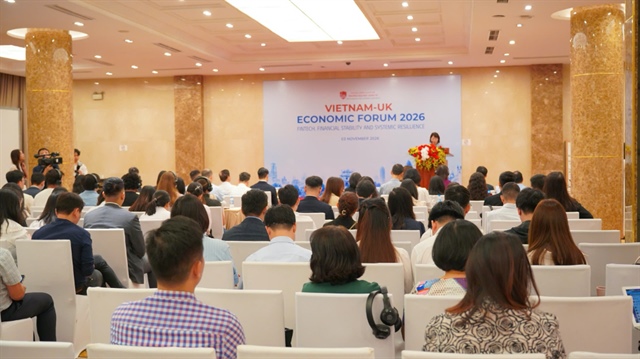
Nguyen Thi Hong Thuy, vice rector of the UEB. Photo: UEB |
This challenge was a central theme at the Vietnam-UK Economic Forum 2026, held in Hanoi on November 3. The event was jointly organised by the University of Economics and Business (UEB) under Vietnam National University, Hanoi, the Vietnam-UK Friendship Association, and partners.
According to Nguyen Thi Hong Thuy, vice rector of the UEB, the financial system is undergoing profound transformation, with fintech, AI, big data, cloud computing, digital assets, and open finance fundamentally changing how financial services are designed, delivered, and supervised.
“Technology can reduce transaction costs, expand access to finance, improve the operational efficiency of financial institutions, and create products and services that were previously difficult to imagine,” she said.
Yet these opportunities come with emerging risks involving cybersecurity, data management, AI models, third-party technology providers, and digital assets. As financial institutions become more interconnected, disruptions can also spread more rapidly across the system.
“The question today is no longer simply how to innovate faster, but how to innovate safely and resiliently,” she said.
From digital transactions to business model transformation
One of the most significant changes is the shift from digitising individual transactions towards transforming the core business models of financial institutions. In the early stages, digital transformation largely focused on mobile banking, electronic payments, and process automation. Today, technology is increasingly being integrated into core banking activities, including data analytics, risk management, lending, and investment decisions.
AI is being used to detect fraud, assess creditworthiness, manage portfolios, and personalise financial services. Meanwhile, Open Banking and application programming interfaces are expanding connections between banks and external partners, while cloud computing enables financial institutions to scale operations more flexibly.
These developments mean that digital transformation is no longer simply a technology issue. It requires fundamental changes to business models, data architecture, workforce capabilities, and governance systems.
This also calls for a broader approach to risk management. In an increasingly digital financial system, a technology failure can quickly become an operational, liquidity, or reputational issue, potentially affecting financial stability.
A bank may have invested heavily in cybersecurity but remain vulnerable if it relies excessively on a single cloud service provider, operates with fragmented data, or lacks employees capable of responding effectively to system disruptions.
Against this backdrop, operational resilience is becoming increasingly important. Rather than focusing solely on preventing disruptions, financial institutions must ensure that critical services can continue operating, losses can be contained, and systems can recover quickly when incidents occur.
“The question is not only whether we can prevent every disruption, but also whether, when disruption happens, the system can continue delivering critical services, limit the damage, and recover quickly enough,” Thuy said.
For regulators, the challenge is to strike an appropriate balance between innovation and stability, openness and security, as well as speed and resilience.
An overly rigid regulatory framework may slow innovation, while innovation without adequate safeguards can expose consumers and the wider financial system to new risks. Regulatory sandboxes, regulatory technology, supervisory technology, and AI governance are among the tools that can help address this challenge.
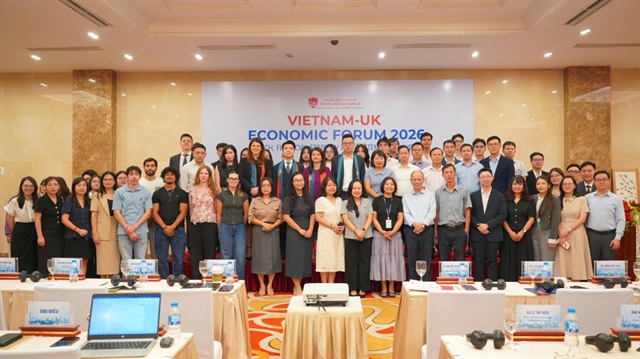
Alexandra Smith, chargé d'affaires at the British Embassy in Vietnam. Photo: UEB |
UK experience offers lessons for responsible innovation
Sharing the UK's experience, Alexandra Smith, chargé d'affaires at the British Embassy in Vietnam, said digital payments, AI, and other emerging technologies were creating significant opportunities to improve efficiency, widen access to financial services, and boost financial inclusion.
However, innovation must be supported by appropriate safeguards to maintain financial stability, protect consumers, and preserve market confidence.
The UK has sought to create an environment in which financial innovation can flourish while maintaining effective regulatory oversight. One example is the Financial Conduct Authority's regulatory sandbox, which allows businesses to test new financial products and services in a safe and controlled environment.
The UK also places considerable emphasis on responsible adoption of emerging technologies, cybersecurity, and operational resilience, areas in which it is keen to share its experience as Vietnam continues developing its financial ecosystem.
Smith noted that successful financial development required much more than technology, investment, and infrastructure. Strong institutions, skilled professionals, and continuous exchanges of knowledge and expertise were equally important.
Universities, she added, played a significant role in developing talent, boosting research, and identifying practical solutions to emerging challenges.
“We are not here just to share experience. We are here to learn from Vietnam, too, from Vietnam's priorities, ambitions, and the partnerships it wishes to develop,” she said and expressed hopes for expanded bilateral cooperation, particularly through joint research initiatives that could combine Vietnam's dynamism and ambitions with the UK's expertise and international connections.
|
Photo: UEB |
Vietnamese banks face gaps between digitalisation and customer experience
Sharing findings from a study on digital transformation readiness and operational resilience across 20 Vietnamese commercial banks, Do Quang Vinh, vice chairman and deputy CEO of SHB,
presented findings from a study on digital transformation readiness and operational resilience across 20 domestic commercial banks.
The findings show that banks have made significant progress in developing digital payments. However, the deployment of digital platforms does not necessarily guarantee a stable service experience.
According to Vinh, customers do not usually distinguish whether a problem originates from an application, a payment system, or the underlying infrastructure. They simply expect services to operate instantly and continuously. Disruptions during peak hours can directly affect customers’ perceptions of service quality.
Another bottleneck lies in banks’ ability to leverage data, while technological resources remain a factor contributing to differences in digital transformation readiness among banking groups.
“Banks cannot focus solely on expanding digital transaction channels; they must also continue to optimise their underlying infrastructure. While customer-facing interfaces and services have advanced rapidly, core systems, integration capabilities, and data sharing still require investment to ensure seamless and stable operations,” Vinh said.
Alongside technology, SHB considers human resources another significant challenge. Digital transformation requires not only investment in technology but also changes in how banks train and support employees, and organise their work.
“The pace of technology deployment must go hand in hand with employees’ ability to adapt. Otherwise, continuous changes could create additional pressure and disrupt operational processes,” he added.
The initial benefits of digital transformation are more evident in process optimisation and productivity gains, while improvements in service quality, personalisation, and incident handling still require further time and investment.
Based on the research findings, Vinh said the next phase of digital transformation in banking should shift its focus from transaction digitalisation towards data utilisation, AI applications, and the integration of service ecosystems.
“Internal efficiency gains need to be translated into better customer experiences, while staff training must become an ongoing process, tailored to individual roles and the technological changes taking place in day-to-day operations,” he said.
Resilience cannot be assessed solely by the security of technological infrastructure. Data needs to be integrated, systems must be user-friendly, incident reporting and response mechanisms must be effective, and employees must be able to adapt when disruptions occur.
- 15:52 03/11/2026